
Commercial Auto Insurance in Ohio & Pennsylvania
Coverage for work trucks, fleets, and any vehicle used for business purposes.
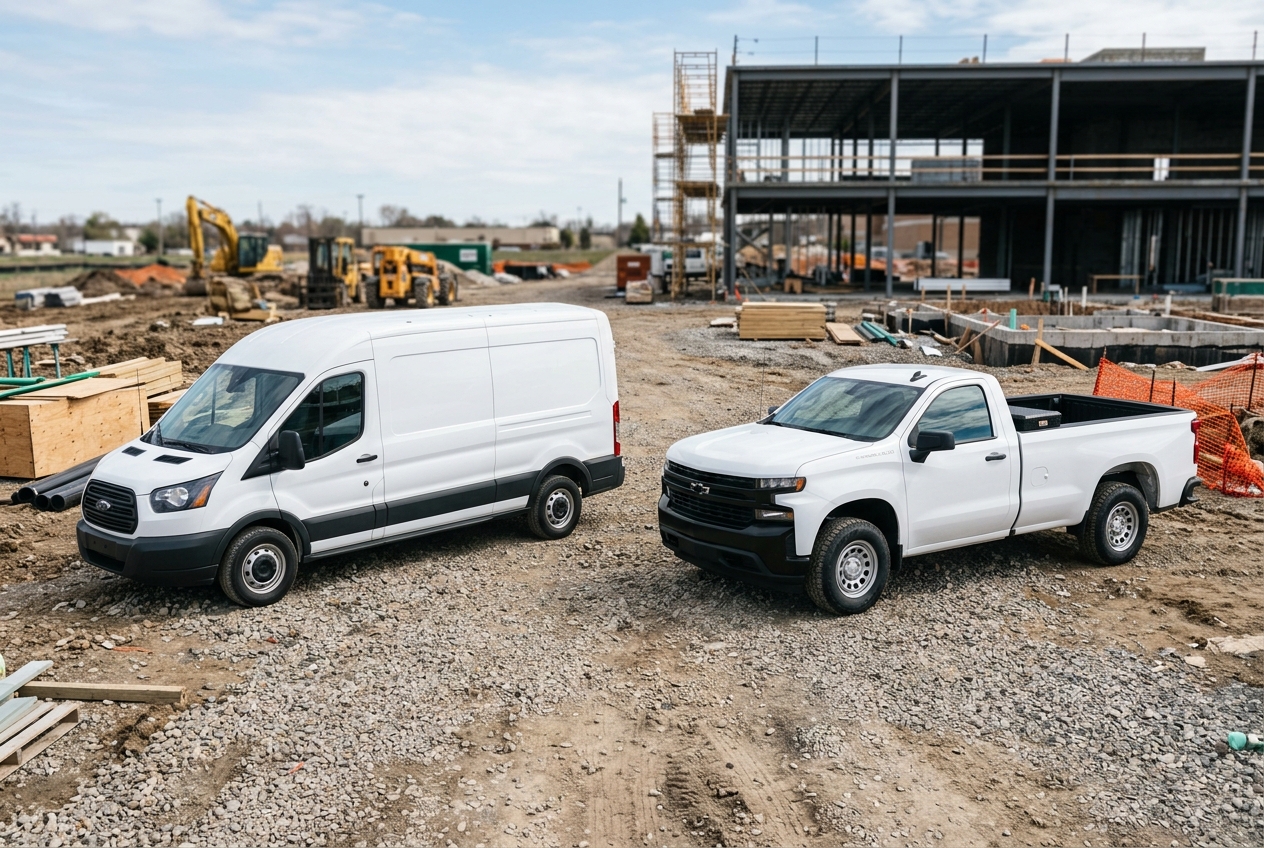
Personal auto policies exclude business use. If your vehicle is titled to a business, hauls tools to job sites, or makes deliveries, you almost certainly need commercial auto insurance. We write commercial auto through Progressive Commercial, Travelers, Liberty Mutual, Sentry, Berkshire Hathaway, and more — matching the right specialty market to your operation.
What Commercial Auto Insurance Covers
Core coverage components we'll review and tailor on your quote.
Liability ($1M Combined Single Limit)
Bodily injury and property damage you cause to others while operating a business vehicle. $1M CSL is the professional standard.
Physical Damage (Collision + Comprehensive)
Repairs your vehicle after an accident, theft, vandalism, or weather event.
Hired & Non-Owned Auto (HNOA)
Extends coverage to rented vehicles and employees' personal vehicles used for business — usually only ~$150/year extra.
Uninsured/Underinsured Motorist
Protects your business when the at-fault driver has too little or no insurance.
Medical Payments / PIP
Pays medical bills for driver and passengers.
Optional Add-Ons Worth Considering
- MCS-90 endorsement (for DOT-regulated trucks)
- Cargo insurance for hauling freight
- Tools and equipment coverage (inland marine)
- Rideshare endorsement for personal-auto-with-Uber drivers
- Roadside / towing for commercial vehicles
Common Exclusions (What's Usually NOT Covered)
Knowing what your policy doesn't cover is just as important.
- Personal use of personal vehicles (separate personal auto required)
- Wear and tear, mechanical breakdown
- Cargo damage without inland marine coverage
- Liability over the policy limit (need commercial umbrella)
Who Really Needs This Coverage
- Vehicles titled to a business (LLC, INC, etc.)
- Tradespeople hauling tools and materials
- Delivery vehicles — food, supplies, documents
- Vehicles with lettering, wraps, or logos
- Vehicles over 10,000 lbs GVWR
- Rideshare drivers (need endorsement or full commercial)
What Drives Your Premium
Vehicle type and weight class
Light pickups vs. straight trucks vs. tractor-trailers are all priced differently.
Radius of operation
Local <50 mi rates much lower than regional or long-haul.
Driver MVRs
Pulling motor vehicle records on every driver is mandatory — even one bad MVR can spike premium.
Cargo and class code
Hauling intermodal cargo or hazmat rates differently from hauling office supplies.
Frequently Asked Questions
Quick answers about commercial auto insurance in Ohio and Pennsylvania.
Related Insights from Our Blog
Plain-English guides relevant to commercial auto insurance.
Explore Related Coverage
Ready for a real quote on commercial auto insurance?
We'll compare options across 100+ insurance markets and contact you as soon as possible during business hours.
No obligation. No spam. Just a real Ohio agent.