
Landlord & Rental Property Insurance in Ohio & Pennsylvania
DP-3 dwelling fire policies plus liability and loss of rents — written through specialty carriers.
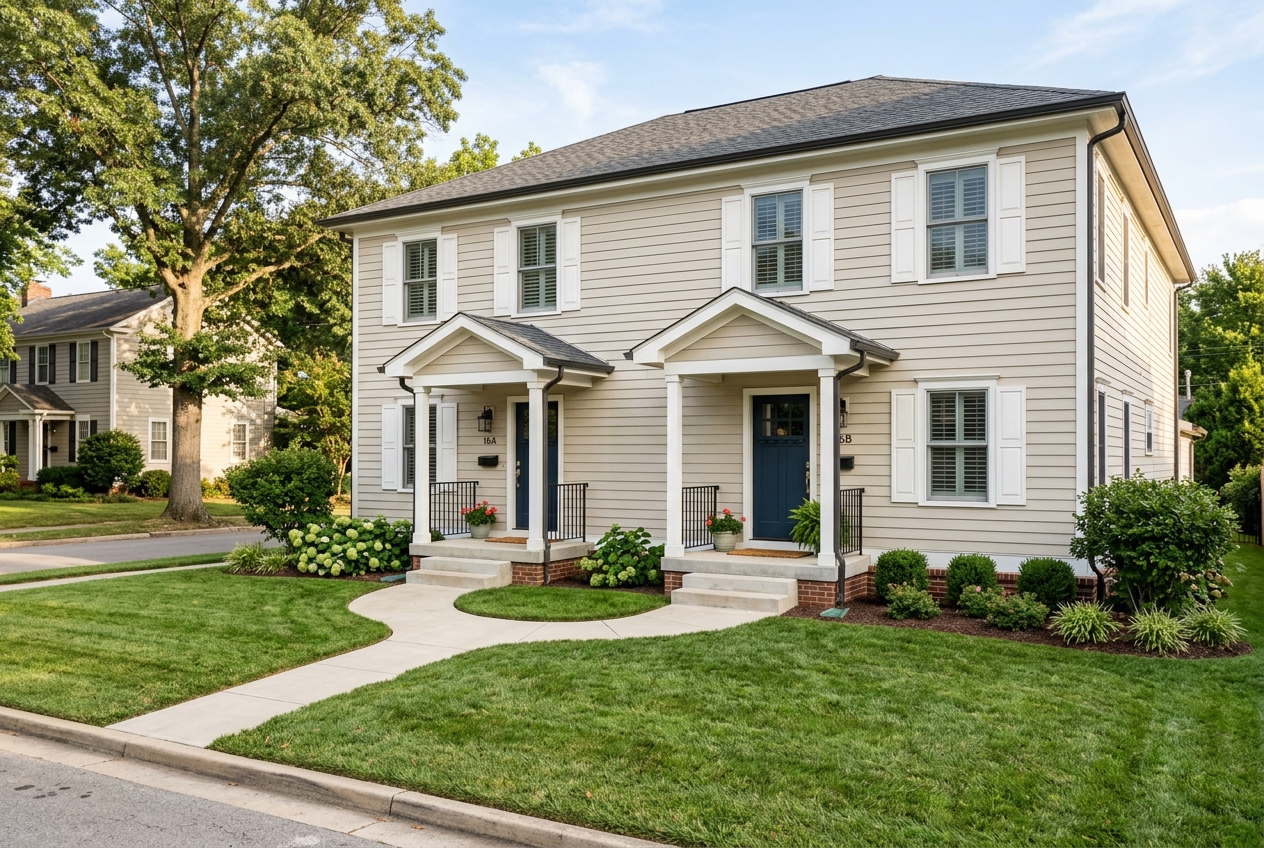
Rental property insurance is fundamentally different from a homeowners policy. Most owners we meet are carrying the wrong coverage — usually a DP-1 with ACV settlement, leaving them tens of thousands of dollars short after a major loss. We write rental properties on DP-3 "special form" policies across specialty carriers like Foremost, Travelers, American Modern, Progressive, and Liberty Mutual.
What Landlord Insurance Covers
Core coverage components we'll review and tailor on your quote.
Dwelling (Coverage A) on Replacement Cost
Covers your rental building on an "open perils" basis — anything is covered unless specifically excluded. The professional standard.
Other Structures
Detached garages, sheds, fences, and outbuildings on the property.
Personal Liability
Protects you from tenant slip-and-fall lawsuits, dog bites, and similar claims. We recommend $500K minimum, $1M+ for portfolios.
Fair Rental Value / Loss of Rents
Pays your rent while the unit is uninhabitable after a covered loss. Carry at least 12 months.
Medical Payments
Small-dollar medical bills for injured guests — no fault required.
Optional Add-Ons Worth Considering
- Vandalism and malicious mischief
- Ordinance or law (for older buildings with code-upgrade exposure)
- Service line coverage (huge in older OH/PA neighborhoods)
- Equipment breakdown
- Umbrella policy stacking over the portfolio
Common Exclusions (What's Usually NOT Covered)
Knowing what your policy doesn't cover is just as important.
- Tenant's personal belongings (their renters policy covers this)
- Flood, earthquake, and most named-storm wind
- Wear and tear, neglect, and pest damage
- Intentional acts by tenants in some cases — sublimits vary
Who Really Needs This Coverage
- All non-owner-occupied rental property owners
- Short-term rental hosts (Airbnb/VRBO) — needs specialty policy
- Owners with multiple properties — schedule on one policy for discounts
- Investors with vacant or rehab properties — needs vacant policy
What Drives Your Premium
Property type and age
Older homes and multi-family buildings rate higher than newer single-families.
Tenant type
Long-term tenants rate better than short-term/Section 8 in most carriers.
Coverage form (DP-1 vs DP-3)
DP-3 costs slightly more but pays out dramatically better.
Deductible and liability limit
$2,500 deductible + $500K liability is the sweet spot.
Frequently Asked Questions
Quick answers about landlord insurance in Ohio and Pennsylvania.
Related Insights from Our Blog
Plain-English guides relevant to landlord insurance.
Explore Related Coverage
Ready for a real quote on landlord insurance?
We'll compare options across 100+ insurance markets and contact you as soon as possible during business hours.
No obligation. No spam. Just a real Ohio agent.