
Workers' Compensation Insurance in Ohio & Pennsylvania
Required employee injury coverage — Ohio BWC and PA private carrier placements.
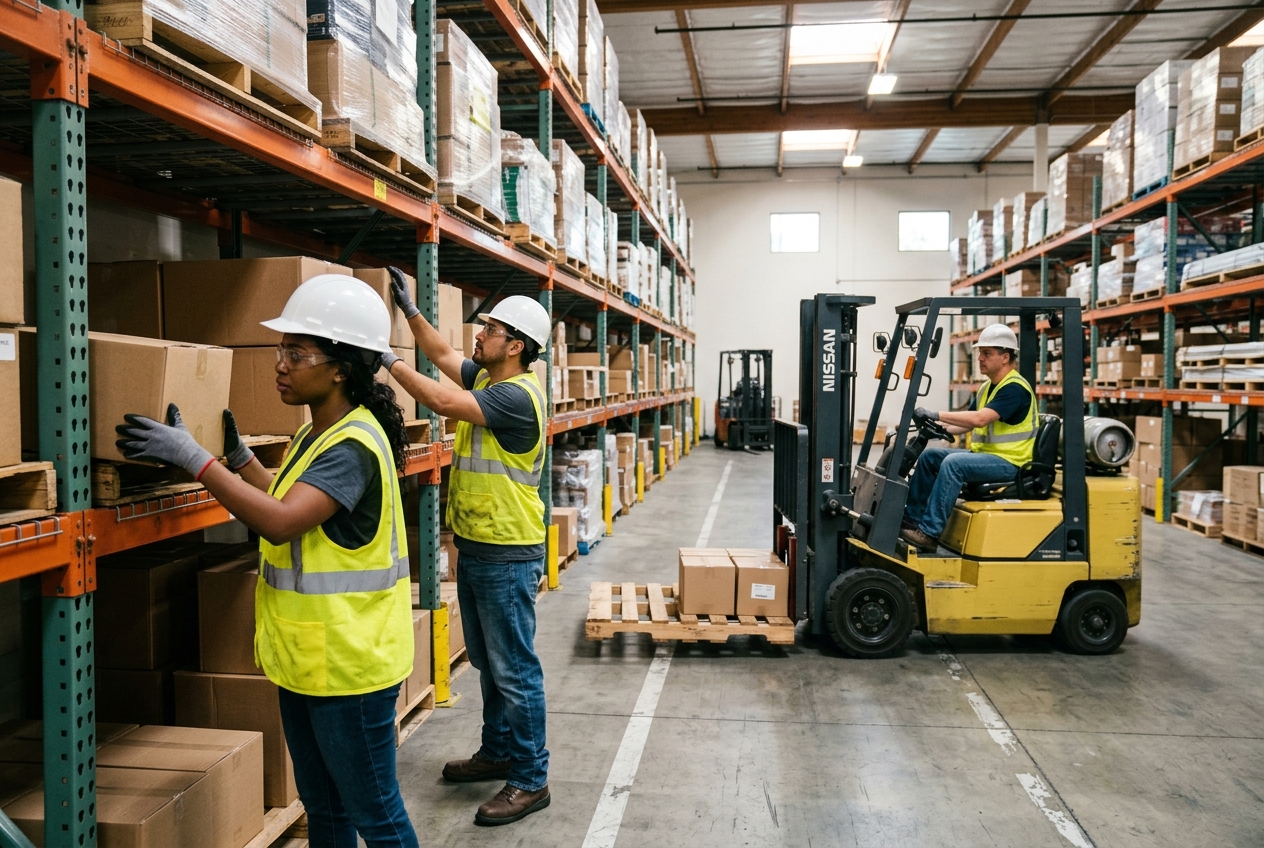
Workers' compensation is mandatory for almost every employer in both Ohio and Pennsylvania. Ohio uses a monopolistic state fund through the Bureau of Workers' Compensation (BWC); Pennsylvania uses private carriers. We help businesses navigate either system, optimize class codes, manage audits, and add the right Employer's Liability stop-gap coverage in Ohio.
What Workers' Compensation Insurance Covers
Core coverage components we'll review and tailor on your quote.
Medical Benefits
Pays all reasonable and necessary medical care for work-related injuries and illnesses — no out-of-pocket for the employee.
Wage Replacement
Pays a portion of lost wages while an injured employee can't work (usually 66 2/3% of average weekly wage).
Permanent Disability
Lump-sum or ongoing payments for lasting impairment from a workplace injury.
Death Benefits
Pays surviving spouse and dependents in cases of fatal workplace accidents.
Employer's Liability (Stop-Gap in OH)
Separate private policy needed in Ohio to cover lawsuits not handled by BWC. PA's private carriers include this automatically.
Optional Add-Ons Worth Considering
- Pay-as-you-go workers' comp (premium based on actual payroll)
- Group rating programs in Ohio (BWC discount)
- Loss prevention services and safety consulting
- Drug-free workplace credits
Common Exclusions (What's Usually NOT Covered)
Knowing what your policy doesn't cover is just as important.
- Self-inflicted injuries
- Injuries from intoxication or illegal drug use
- Injuries off the clock or away from work duties
- Independent contractors (without proper election)
Who Really Needs This Coverage
- Any Ohio employer with 1+ employees (BWC required)
- Any Pennsylvania employer with 1+ employees (private carrier required)
- LLC owners — election may be needed
- Contractors required to show certificates to general contractors and landlords
What Drives Your Premium
Industry class code
Roofers and loggers cost far more than office workers. Class code accuracy is everything.
Annual payroll
Primary rating basis — premium is per $100 of payroll.
Experience modifier (E-Mod)
Past losses raise your E-Mod and premium for years.
Safety programs and audits
Drug-free workplace, safety committees, and audits can significantly lower premium.
Frequently Asked Questions
Quick answers about workers' compensation insurance in Ohio and Pennsylvania.
Related Insights from Our Blog
Plain-English guides relevant to workers' compensation insurance.
Explore Related Coverage
Ready for a real quote on workers' compensation insurance?
We'll compare options across 100+ insurance markets and contact you as soon as possible during business hours.
No obligation. No spam. Just a real Ohio agent.